The Short Answer: Not Necessarily
Height and weight and a diagnosis of sleep apnea are common issues in life-insurance underwriting. Neither automatically means that coverage is unavailable.
What matters is the complete picture: the degree of the concern, whether it is stable or changing, how any condition is being treated, and whether other health factors are present.
This is also an area where carrier guidelines can differ considerably.
How Insurers Look at Height and Weight
Life insurers generally use height-and-weight guidelines, often expressed through build charts or Body Mass Index (BMI), as one part of underwriting.
BMI is simply a relationship between height and weight. It does not tell an underwriter everything about a person’s health, but insurers may use it as one risk indicator.
A higher BMI may affect the rate class offered, particularly when combined with conditions such as diabetes, high blood pressure, cardiovascular disease or sleep apnea. Age and other favorable health factors can also affect how a particular carrier evaluates the case.
Importantly, the cutoff for one underwriting class is not necessarily the same at every insurance company.
What About Sleep Apnea?
Sleep apnea is another condition that often causes people to assume they will be declined.
Underwriters typically want to understand the type and severity of the apnea, the results of a sleep study when available, whether treatment was recommended, and whether the applicant is following that treatment.
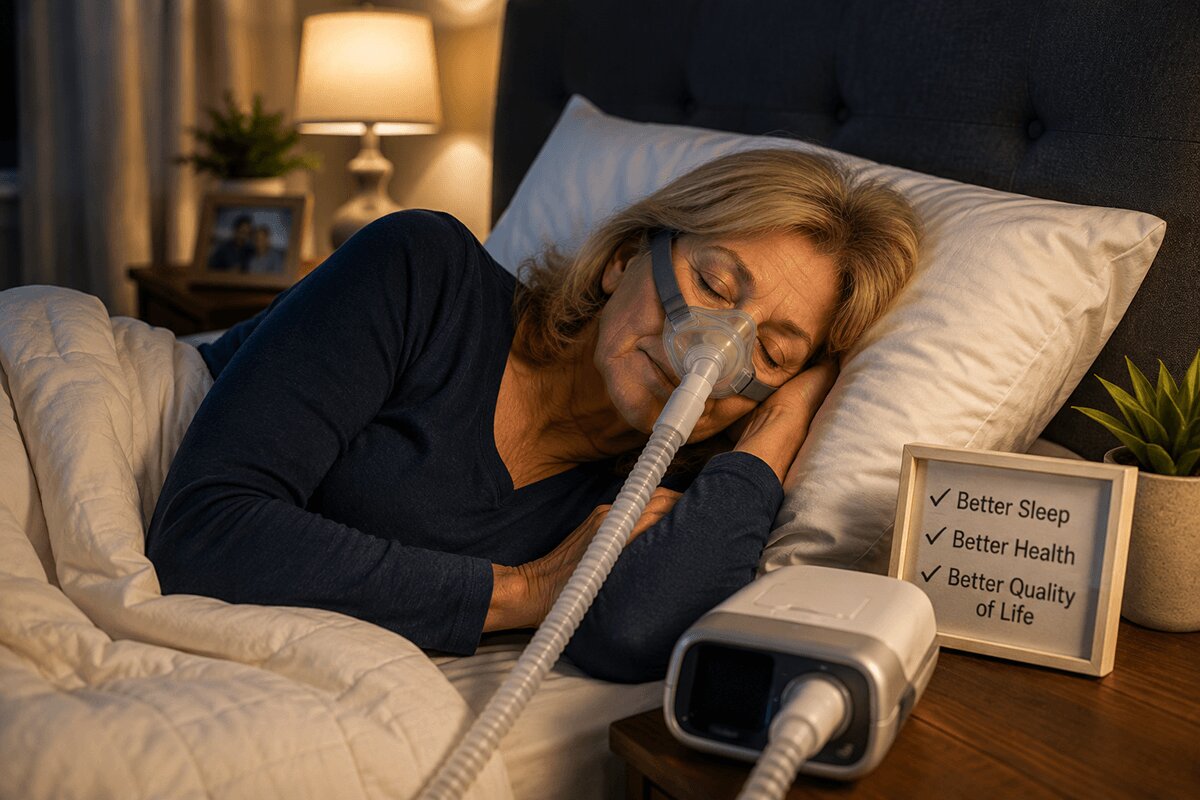
For obstructive sleep apnea, treatment may include CPAP or BiPAP therapy, an oral appliance, weight management or other physician-directed approaches.
A documented history of effective treatment and follow-up can present a very different underwriting picture from severe apnea that remains untreated or poorly controlled.
BMI and Sleep Apnea Are Often Evaluated Together
These two issues sometimes overlap because excess weight can be associated with obstructive sleep apnea.
An underwriter may therefore look beyond a single BMI number or a simple yes/no answer about apnea. Other information can include blood pressure, blood sugar, cardiovascular history, sleep-study findings, treatment compliance and whether weight has been stable.
This is why two applicants of the same height and weight can receive different results – and why two people with sleep apnea can also receive different results.
Why Accurate Information Helps
Before applying, it can be useful to know:
- Your current height and weight.
- Whether your weight has changed significantly in the last year.
- When sleep apnea was diagnosed.
- Whether the apnea was described as mild, moderate or severe.
- Whether you use CPAP, BiPAP, an oral appliance or another prescribed treatment.
- Whether you are consistently following the prescribed treatment.
- Whether you have related conditions such as high blood pressure or diabetes.
- The approximate date of your most recent sleep study or physician follow-up.
These details can help narrow the underwriting possibilities before an application is submitted.
The First Answer Is Not Always the Only Answer
A rate increase or decline from one insurer does not necessarily mean every insurer will respond the same way.
Companies maintain their own underwriting guidelines and appetites for different risks. Depending on the circumstances, an independent agency may be able to compare different carriers, coverage types and underwriting approaches.
Sometimes the appropriate answer is to apply now. Sometimes waiting until additional treatment history or medical follow-up is available may make sense. And sometimes a different type of policy is the better fit.
The Bottom Line
A high BMI or sleep apnea can influence life-insurance underwriting, but neither condition should automatically be treated as a disqualification.
The important questions are how significant the risk is, how well it is being managed, what other health factors are present and which insurer’s guidelines best fit the situation.
Rather than guessing based on one health condition, start by gathering the facts and evaluating the available options.
IMPORTANT INFORMATION
This article is for general educational purposes only and is not intended as medical, legal, tax, investment or individualized insurance advice. Insurance availability, underwriting classifications, premiums, policy features and benefits vary by insurer, product, state and individual circumstances. Any guarantees are subject to the claims-paying ability of the issuing insurance company. Consult the appropriate licensed professional regarding your specific situation.